

TL;DR: A $5,000 contract can expose a business to significant financial risk if it includes unlimited liability or broad indemnity obligations. Liability caps help keep risk proportional, but exceptions and poorly negotiated clauses can leave exposure uncapped. Always review indemnity and limitation-of-liability terms before signing, regardless of contract value.
On paper, it was a straightforward deal. A growing SaaS vendor entered into a modest agreement with a corporate customer. The annual contract value was just $5,000. It was the kind of transaction that happens every day, quickly negotiated, lightly reviewed, and signed without much resistance. The focus was on revenue, growth, and closing the deal efficiently. Legal terms were treated as background noise, standard clauses that rarely attracted serious scrutiny.
But buried within that agreement were provisions that would later define the company’s fate: a broadly drafted indemnity clause and a limitation of liability clause that lacked precision. At the time, neither seemed controversial. Like many “boilerplate” provisions, they were accepted as routine.
For a while, everything worked exactly as expected.
Then, unexpectedly, everything changed.
A vulnerability in the software environment was exploited, leading to unauthorized access to customer data. The incident triggered regulatory attention, legal scrutiny, and reputational damage for the client. What began as a contained technical failure quickly escalated into a legal and financial crisis. The client faced investigations, potential fines, and growing pressure from affected users.
And then came the demand.
The customer turned to the contract and invoked the indemnity clause, arguing that the vendor must cover all losses arising from the breach, including legal fees, settlements, regulatory exposure, and associated damages. The vendor, in turn, looked to the limitation of liability clause for protection.
But the protection was weaker than expected.
The indemnity provision was expansive. The limitation clause did not clearly apply to indemnity obligations. The supposed cap on liability offered little comfort. What had seemed like a controlled legal framework now revealed a dangerous gap.
In that moment, the realization was stark and unavoidable:
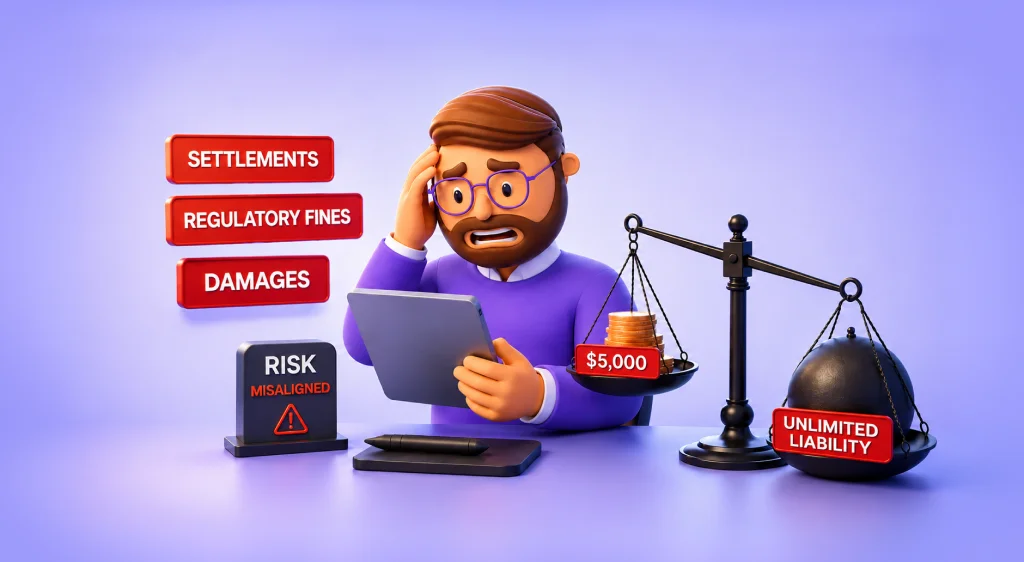
The vendor had taken on potentially unlimited liability for a $5,000 contract.
When contracts lose economic balance
At its core, every contract reflects an underlying economic reality. Risk is traded for reward. Compensation is meant to justify exposure. When properly structured, agreements ensure that liability remains proportionate to the value of the deal.
But when liability becomes unlimited while the contract value remains minimal, that balance collapses.
The consequences are not merely legal; they are fundamentally commercial. A business earning a few thousand dollars from a contract should not, in any rational framework, be exposed to losses running into millions. Yet this is precisely what happens when indemnity clauses are broad and liability caps are either unclear or ineffective.
Such a mismatch creates a distorted risk profile. Instead of allocating risk, the contract amplifies it. Instead of protecting the parties, it exposes one side to unpredictable and potentially catastrophic consequences.
This is not risk management. It is risk misalignment.
The amplifying effect of indemnity
Indemnity clauses play a central role in this imbalance. Unlike general liability provisions, indemnities are designed to shift responsibility for specific losses, often those arising from third-party claims. They frequently extend beyond direct damages to include legal defense costs, settlements, and other downstream liabilities.
Their reach can be expansive, particularly when drafted without careful limitation.
What makes indemnity particularly powerful and dangerous is its potential to operate outside the boundaries of limitation of liability clauses. In many contracts, unless explicitly addressed, indemnity obligations are not subject to the same caps that apply to other forms of liability. This creates a dual structure: one where general liability is controlled, but indemnity remains open-ended.
In practice, this means a company may believe its exposure is limited, only to discover at the worst possible moment that its most significant obligations fall outside that limit.
The result is a contractual framework where the most important risks are the least controlled.
Why unlimited liability is rarely justifiable
From a commercial perspective, unlimited liability in a low-value contract is fundamentally difficult to justify. Businesses operate by pricing risk. They assess potential exposure, incorporate it into their pricing model, and ensure that the rewards justify the risks undertaken.
This model breaks down entirely when liability is uncapped.
An uncapped obligation is, by definition, unpredictable. It cannot be reliably priced, estimated, or hedged. No rational business can sustainably operate on the assumption that a modest contract might generate liabilities far exceeding its total revenue base. At that point, the transaction ceases to be commercially viable.
Compounding this issue is the role of insurance. Many businesses rely on insurance coverage to support their contractual obligations. However, insurance policies come with limits, exclusions, and conditions. Certain types of losses, such as regulatory fines or reputational harm, may not be covered at all. Where contractual liability exceeds insurance coverage, the business is left carrying unfunded risk exposure with no financial backstop.
This gap between contractual promises and financial reality is where significant danger lies.
For smaller companies and startups, the consequences can be existential. A single large claim can overwhelm cash reserves, erode investor confidence, and threaten the viability of the business itself. What began as an ordinary agreement can quickly escalate into a crisis that determines whether the company survives.
How these risks are created
Importantly, unlimited liability in such scenarios is rarely a deliberate choice. It is more often the result of oversight. Standard templates are reused without sufficient customization. Negotiations focus on commercial terms, while legal provisions are accepted without detailed consideration. The interaction between indemnity and limitation clauses is not fully examined.
In many cases, the parties assume the contract is balanced simply because it appears familiar.
But contracts do not fail in ordinary circumstances. They are tested when something goes wrong. And it is only then that the true meaning and impact of their provisions becomes clear.
Restoring balance through thoughtful drafting
The solution is not to eliminate indemnities or overly restrict liability. Both serve essential functions in risk allocation. Rather, the goal is to ensure that they operate together in a coherent and balanced manner.
A well-drafted agreement aligns liability with the value of the contract. It ensures that caps are meaningful, clearly defined, and applicable to the risks that matter most. It distinguishes between categories of risk, treating routine operational issues differently from exceptional circumstances such as fraud or willful misconduct.
Equally important is clarity. The contract must explicitly state whether indemnity obligations are subject to liability caps. It must avoid ambiguity that could lead to conflicting interpretations. Precision in drafting is not merely a legal preference; it is a practical necessity.
Finally, contractual obligations should be aligned with financial capacity, including insurance coverage. Promises made on paper should be supported by realistic mechanisms for fulfillment.
Conclusion
Unlimited liability in a $5,000 contract is not a reflection of strong legal protection. It is a sign of imbalance. It indicates that risk has not been properly calibrated to reward, and that the contract may expose one party to consequences far beyond what was ever intended.
Indemnity and limitation of liability are not opposing tools; they are complementary mechanisms designed to work together. One assigns responsibility, the other defines its boundaries. When properly aligned, they create certainty and enable confident commercial relationships. When misaligned, they create exposure and uncertainty.
The lesson is simple, but critical.
Contracts must not only be legally sound; they must make economic sense.
Because when a crisis occurs, the true test of a contract is not how it reads, but whether the outcome it produces is one the parties can survive.
Ready to simplify secure document signing? Try a free BoldSign trial and explore our complete eSignature platform.
Need help? Schedule a demo or contact our support team via our support portal.